- 715 Actual Exam Questions
- Compatible with all Devices
- Printable Format
- No Download Limits
- 90 Days Free Updates
Get All CFA Level II Chartered Financial Analyst Exam Questions with Validated Answers
| Vendor: | CFA Institute |
|---|---|
| Exam Code: | CFA-Level-II |
| Exam Name: | CFA Level II Chartered Financial Analyst |
| Exam Questions: | 715 |
| Last Updated: | October 8, 2026 |
| Related Certifications: | CFA Level II |
| Exam Tags: |
Looking for a hassle-free way to pass the CFA Institute CFA Level II Chartered Financial Analyst exam? DumpsProvider provides the most reliable Dumps Questions and Answers, designed by CFA Institute certified experts to help you succeed in record time. Available in both PDF and Online Practice Test formats, our study materials cover every major exam topic, making it possible for you to pass potentially within just one day!
DumpsProvider is a leading provider of high-quality exam dumps, trusted by professionals worldwide. Our CFA Institute CFA-Level-II exam questions give you the knowledge and confidence needed to succeed on the first attempt.
Train with our CFA Institute CFA-Level-II exam practice tests, which simulate the actual exam environment. This real-test experience helps you get familiar with the format and timing of the exam, ensuring you're 100% prepared for exam day.
Your success is our commitment! That's why DumpsProvider offers a 100% money-back guarantee. If you don’t pass the CFA Institute CFA-Level-II exam, we’ll refund your payment within 24 hours no questions asked.
Don’t waste time with unreliable exam prep resources. Get started with DumpsProvider’s CFA Institute CFA-Level-II exam dumps today and achieve your certification effortlessly!
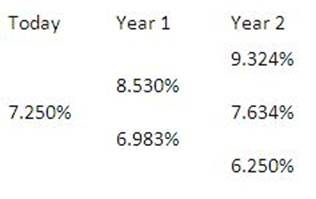
Mike Diffle has been asked to evaluate the bonds of Hardin, Inc. The specific issue Diffle is considering has an 8% annual coupon and matures in two years. The bonds are currently callable at 101, and beginning in six months, they are callable at par. Bratton Corp, a competitor of Hardin's, also has bonds outstanding which are identical to Hardin's except that they are not callable. Diffle believes that the AA rating of both bonds is an accurate reflection of their credit risk. Diffle is wondering if the Bratton bonds might be a better investment than the Hardin bonds. Assume that the following 1-year interest rate tree is used to value bonds with a maturity of up to three years (this tree assumes interest rate volatility of 10%).

Also, assume that the appropriate spot rates for securities maturing in one, two, and three years are 7.25%, 7.5%, and 7.80%, respectively.
Diffle believes he should begin his analysis with the option-free Bratton bonds. He decides to consider two different approaches to valuing the Bratton Bonds---one that uses the current spot rate curve and another that uses the interest rate tree given above.
For the next step in his analysis, Diffle has decided to calculate the value of the Hardin bonds using the interest rate tree. His assumption is that the bond will be called ai any node of the tree where the calculated value exceeds the call price. Diffle summarizes the results of his bond valuation analysis in a memo to his supervisor, Luke Puldo. In this memo, Diffle makes the following statements:
Statement 1: The value of the option embedded in the Hardin bonds can be derived by simply subtracting the interest rate tree value of the Hardin bonds from the interest rate tree value of the Bratton bonds.
Statement 2: I am concerned that the 10% volatility assumption used to develop the interest rate tree might be too low. A higher volatility assumption would result in a lower value for the Hardin bonds.
After reviewing Diffle's analysis, Puldo notes that Diffle has not included any information on the option adjusted spread (OAS) for the Hardin bonds. Puldo suggests that Diffle should evaluate the OAS in order to get an idea of the liquidity risk of the Hardin bonds. Diffle counters that the OAS may not be very informative in this case, since he is uncertain as to the reliability of the interest rate volatility assumption.
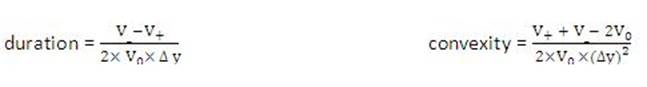
To finish his analysis, Diffle would like to use his binomial model to evaluate the interest rate risk of both the Hardin bonds and the Bratton bonds. Diffle has shocked interest rates by 25 basis points throughout the interest rate tree he has been using to value the two bond issues. Using the new rates, Diffle has calculated values for the bonds assuming a 25-basis-point increase or decrease in rates. He plans to use these values as inputs into the following formulas for duration and convexity:

Which of the following statements is most accurate regarding Diffle's calculation of duration and convexity?
The duration formula given will calculate the percentage change in price for a 100 basis point change in yield, regardless of the actual change in rates used to derive BV_ and BV#. Using the binomial model, the derived values of BV and BV# will take into account any potential change in cash flows due to embedded options. (Study Session 14, LOS 54.h)
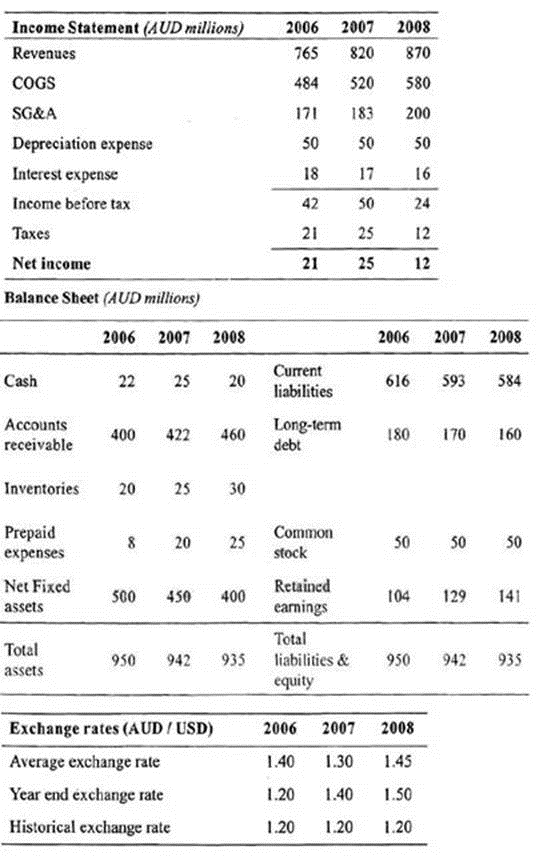
Gary Smith, CFA, has been hired lo analyze a specialty tool and machinery manufacturer, Whitmore Corporation (WMC). WMC is a leading producer of specialty machinery in the United States. At the end of 2006, WMC purchased York Tool Company (YTC), an Australian firm in a similar line of business. YTC has partially integrated its marketing functions within WMC but still maintains control of its operations and secures its own financing. Following is a summary of the income statement and balance sheet for YTC (in millions of Australian dollars - AUD) for the past three years as well as exchange rate data over the same period.

Smith has discovered that WMC has a small subsidiary in Ukraine. The Subsidiary follows IAS accounting rules and uses FIFO inventory accounting. The Ukrainian subsidiary was acquired ten years ago and has been fully integrated into WMC's operations. WMC obtains funding for the subsidiary whenever the company finds profitable investments within Ukraine or surrounding countries. According to forecasts from economists, the Ukrainian currency is expected to depreciate relative to the U .S . dollar over the next few years. Local currency prices are forecasted to remain stable, however.
One of the managers at WMC asks Smith to analyze a third subsidiary located in India. The manager has explained that real interest rates in India over the last three years have been 2.00%, 2.50%, and 3.00%, respectively, while nominal interest rates have been 34.64%, 29.15%, and 25.66%, respectively. Smith requests more time to analyze the Indian subsidiary.
Determine whether the translation method appropriate for consolidating the Ukrainian subsidiary's financial statements would allow WMC to recognize unrealized and realized gains in nonmonetary assets owned by the subsidiary.
The appropriate translation method for the Ukrainian subsidiary is the temporal method since the functional currency is the U .S . dollar (the parent's currency). Under the temporal method, realized gains or losses on nonmonetary assets are recognized in operating profits through depreciation and cost of goods sold. Unrealized gains or losses in nonmonetary assets are not recognized under the temporal method. (Study Session 6, LOS 23-c)
Sampson Aerospace is a publicly-traded U .S . manufacturer. Sampson supplies communication and navigation control systems to manufacturers of airplanes for commercial and government use. The company operates two divisions: Commercial Operations and Government Operations. Revenues from the Government Operations division comprise 80% of Sampson's total company revenues. Revenues for other companies in the industry are also driven primarily by sales to the U .S . government.
Sampson has gained a reputation for offering unique products and services. Sampson's market share has been increasing, and its net profit margin is among the highest in its industry.
As part of its business strategy, Sampson seeks out opportunities to enhance internal growth by acquiring smaller companies that possess new technologies that would allow Sampson to offer unique products and services. To this end, Sampson CEO, Drew Smith, recently asked his acquisitions team to consider the purchase of a controlling interest in either NavTech or Aerospace Communications, both software applications firms. Smith provides his acquisitions team with an aerospace analyst's industry report that addresses many key issues within the industry. Selected passages from the report are reproduced below:
Sales in the aerospace electronics industry depend primarily on government military spending, which, in turn, depends on defense budgets. Sales depend on commercial travel to a much lesser extent. The government defense spending budget outlook is fairly bleak as the current administration is looking for ways to reduce the budget deficit. We feel the commercial airline segment has more upside than downside, especially as the global economy improves, so we might see a gradual shift in industry focus toward the commercial airline sector. Companies that already have a foothold in the commercial sector are well-positioned to grow during the global recovery. Even so, companies in this industry will remain highly sensitive to government spending for their revenues. Research and development costs are high and the industry is highly capital intense. While there are only a few companies in this industry, good opportunities exist, especially for companies that have developed sustainable profits through wise acquisitions, cost containment, and the ability to secure long-term government contracts.
Sampson Aerospace recently announced that it is reducing its investment return assumption on its pension assets from 6% to 5%, and that it has entered negotiations to possibly acquire controlling equity interests in communications software firms, NavTech and Aerospace Communications. NavTech recently has decided to capitalize a significant portion of its research and development expense, and Aerospace Communications has restructured and reclassified many of its leases from operating to financial leases. Sampson CEO Drew Smith recently announced that Sampson had dropped out of negotiations with Knowledge Technologies, claiming it was likely not a sustainable business model.
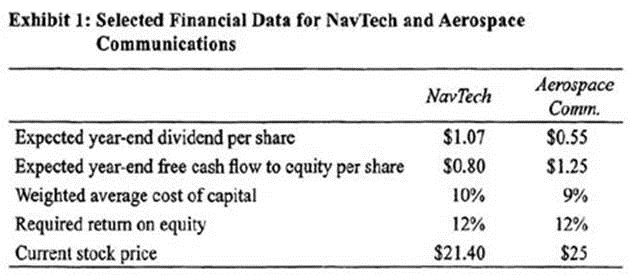
Consensus forecasts for NavTech and Aerospace Communications are presented in Exhibit 1.

Which of the following is most likely a negative factor in assessing the profitability of Sampson over the medium to long term?
Since 80% of Sampsons business is with one customer (the U .S . government), we can expect a great deal of bargaining power from that customer. The government will likely use competitive bidding to encourage strong price competition. There is no indication that suppliers have great bargaining power. The threat of new entrants is likely low because of barriers to entry, including high capital expenditures required to enter the industry and perhaps proprietary knowledge about production and company-owned patents. (Study Session 11, LOS 37.b)
Charles Connor, CFA, is a portfolio manager at Apple Investments, LLC . Apple is a U .S .-based firm offering a wide spectrum of investment products and services. Connor manages the Biogene Fund, a domestic equity fund specializing in small capitalization growth stocks. The Biogene Fund generally takes significant positions in stocks, commonly owning 4.5-5% of the outstanding shares. The fund's prospectus limits positions to a maximum of 5% of the shares outstanding. The performance of the Biogene Fund has been superior over the last few years, but for the last two quarters the fund has underperformed its benchmark by a wide margin. Connor is determined to improve his performance numbers going forward.
The Biogene prospectus allows Connor to use derivative instruments in his investment strategy. Connor frequently uses options to hedge his fund's exposure as he builds or liquidates positions in his portfolio since Biogene's large positions often take several weeks to acquire. For example, when he identifies a stock to buy, he often buys call options to gain exposure to the stock. As he buys the stock, he sells off the options or allows them to expire. Connor has noticed that the increased volume in the call options often drives the stock price higher for a few days. He has seen a similar negative effect on stock prices when he buys large amounts of put options.
The end of the quarter is just a few days away, and Connor is considering three transactions:
Transaction A: Buying Put Options on Stock A
The Biogene Fund owns 4,9% of the outstanding stock of Company A, but Connor believes the stock is fully valued and plans to sell the entire position. He anticipates that it will take approximately 45 trading days to liquidate the entire Biogene position in Stock A
The Biogene Fund owns 5% of the outstanding stock of Company B . Connor believes there is significant appreciation potential for Stock B, but the stock price has dropped in recent weeks. Connor is hoping that by taking an option position, there will be a carryover effect on ihe stock price before quarter end.
Transaction C: Selling the Biogene Fund's Entire Position in .Stock C
Connor believes that Stock C is still attractive, but he is selling the stock with the idea that he will repurchase the position next month. The motivation for the transaction is to capture a capital loss that will reduce the Biogene Fund's tax expense for the year.
Apple has an investment banking department that is active in initial public offerings (IPOs). George Arnold, CFA, is the senior manager of the IPO department. Arnold approached Connor about Stock D, a new IPO being offered by Apple. Stock D will open trading in two days. Apple had offered the IPO to all of its clients, but approximately 20% of the deal remained unsold. Having read the prospectus, Connor thinks Stock D would be a good fit for his fund, and he expects Stock D to improve his performance in both the short and long term. Connor is not aware of any information related to Stock D beyond that provided in the prospectus. Connor asked to purchase 5% of the IPO, but Arnold limited Biogene's share to 2%, explaining:
"With Biogene's reputation, any participation will make the unsold shares highly marketable. Further, we may need Biogene to acquire more Stock D shares at a later date if the price does not hold up."
Connor is disappointed in being limited to 2% of the offering and suggests to Arnold in an e-mail that, given the 2% limitation, Biogene will not participate in the IPO . Arnold responded a few hours later with the following message:
"I have just spoken with Ms. D, the CFO of Stock D . Although it is too late to alter the prospectus, management believes they will receive a large contract from a foreign government that will boost next year's sales by 20% or more. I urge you to accept the 2%---you won't be sorry!"
After reviewing Arnold's e-mail, Connor agrees to the 2% offer.
By executing Transaction C, Connor is:
Transactions meant to minimize tax liabilities are not prohibited by the Standards. If the Biogenc Fund benefits, the investors in the fund will presumably benefit also.
Martin Hagemann, CFA, works for a large brokerage firm in Frankfurt, Germany. Hagemann has been hired by Tryssen AG, a global research-based company that is preparing to go public after a long history of operating privately. The need to raise substantial amounts of capital to fund research and development activities is seen as the key motivation for the change in policy. Tryssen is engaged in the discovery, development, manufacture, marketing, and sale of medical products.
Hagemann's first task is to recommend an exchange upon which Tryssen stock can be traded. One possibility is the Deutsche Bourse. The Deutsche Bourse operates primarily as a continuous order-driven system. Another alternative that Tryssen is considering is to list on a different exchange that operates as a price-driven system.
As an alternative, Tryssen may choose to list as an American Depository Receipt (ADR). ADRs are negotiable U .S . securities that usually represent a non-U .S . based company's publicly traded equity. Although typically denominated in U .S . dollars, depository receipts can also be denominated in euros. Depository receipts can be eligible to trade on all U .S . stock exchanges as well as on many European stock exchanges.
The increasing demand for depository receipts is driven by the desire of individual and institutional investors to diversify their portfolios, reduce risk and invest internationally in the most efficient manner possible. While most investors recognize the benefits of global diversification, there are many challenges presented when investing directly in local trading markets. Obstacles can include inefficient trade settlements, uncertain custody services, and costly currency conversions. Depository receipts overcome many of the inherent operational and custodial hurdles inherent in international investing. Tryssen has decided to access the U .S . market by involving itself in an ADR program. Tryssen has decided to save itself a lot of trouble, however, by not complying with SEC registration and reporting requirements.
As an alternative to ADRs, investors interested in increasing their exposure to international investments can choose to acquire exchange traded funds (ETFs). Hagemann researches the advantages and disadvantages of ETFs.
Execution costs are always a concern, and perhaps even more so for international investors. At the present time, Tryssen AG is most concerned with how reliably it can estimate trading costs. As part of the cost estimation process, Hagemann is asked to provide a report on the advantages and disadvantages of techniques used to reduce execution costs.
Trysse AG proceeds to list on the Frankfurt exchange, and a U .S . affiliate of Hagemann's company starts to aggressively promote the stock. A U .S . investor buys 200 shares of Tryssen at a price of 20 per share. At time of purchase, the exchange rate is 1 = $1.15. One month later Tryssen pays a dividend of 0.25 per share, and investors are subject to a withholding tax of 20%. The U .S . investor is eligible to claim a tax credit of $0.06 per share. At the time the dividend was paid, the shares had jumped to 24 each and the U .S . dollar had weakened to 1 = $ 1.20. The shares were sold just after the dividend was paid.
Which of the following best describes a comparative advantage of a price-driven system over an order-driven system?
It is generally difficult to execute block trades on order-driven systems due to the lack of depth in the market. Order-driven systems do tend to be less costly to operate, however. There is no central order book in a price-driven system; instead, dealers post bid-ask quotes. Finally, in a price-driven system, the dealer provides rather than receives a free option when a firm quote is posted. (Study Session 10, LOS 34.b)
Security & Privacy
Satisfied Customers
Committed Service
Money Back Guranteed