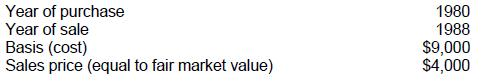AICPA CPA-Regulation Exam Dumps

Get All CPA Regulation Exam Questions with Validated Answers

CPA-Regulation Pack
Vendor: AICPA
Exam Code: CPA-Regulation
Exam Name: CPA Regulation
Exam Questions: 69
Last Updated: October 4, 2026
Related Certifications: Certified Public Accountant
Exam Tags: AICPA Managment
Gurantee
  • 24/7 customer support
  • Unlimited Downloads
  • 90 Days Free Updates
  • 10,000+ Satisfied Customers
  • 100% Refund Policy
  • Instantly Available for Download after Purchase

Get Full Access to AICPA CPA-Regulation questions & answers in the format that suits you best

PDF Version

$40.00
$24.00
  • 69 Actual Exam Questions
  • Compatible with all Devices
  • Printable Format
  • No Download Limits
  • 90 Days Free Updates

Discount Offer (Bundle pack)

$80.00
$48.00
  • Discount Offer
  • 69 Actual Exam Questions
  • Both PDF & Online Practice Test
  • Free 90 Days Updates
  • No Download Limits
  • No Practice Limits
  • 24/7 Customer Support

Online Practice Test

$30.00
$18.00
  • 69 Actual Exam Questions
  • Actual Exam Environment
  • 90 Days Free Updates
  • Browser Based Software
  • Compatibility:
    supported Browsers

Pass Your AICPA CPA-Regulation Certification Exam Easily!

Looking for a hassle-free way to pass the AICPA CPA Regulation exam? DumpsProvider provides the most reliable Dumps Questions and Answers, designed by AICPA certified experts to help you succeed in record time. Available in both PDF and Online Practice Test formats, our study materials cover every major exam topic, making it possible for you to pass potentially within just one day!

DumpsProvider is a leading provider of high-quality exam dumps, trusted by professionals worldwide. Our AICPA CPA-Regulation exam questions give you the knowledge and confidence needed to succeed on the first attempt.

Train with our AICPA CPA-Regulation exam practice tests, which simulate the actual exam environment. This real-test experience helps you get familiar with the format and timing of the exam, ensuring you're 100% prepared for exam day.

Your success is our commitment! That's why DumpsProvider offers a 100% money-back guarantee. If you don’t pass the AICPA CPA-Regulation exam, we’ll refund your payment within 24 hours no questions asked.
 

Why Choose DumpsProvider for Your AICPA CPA-Regulation Exam Prep?

  • Verified & Up-to-Date Materials: Our AICPA experts carefully craft every question to match the latest AICPA exam topics.
  • Free 90-Day Updates: Stay ahead with free updates for three months to keep your questions & answers up to date.
  • 24/7 Customer Support: Get instant help via live chat or email whenever you have questions about our AICPA CPA-Regulation exam dumps.

Don’t waste time with unreliable exam prep resources. Get started with DumpsProvider’s AICPA CPA-Regulation exam dumps today and achieve your certification effortlessly!

Free AICPA CPA-Regulation Exam Actual Questions

Question No. 1

Tom and Joan Moore, both CPAs, filed a joint 1994 federal income tax return showing $70,000 in taxable income. During 1994, Tom's daughter Laura, age 16, resided with Tom. Laura had no income of her own and was Tom's dependent.

Determine the amount of income or loss, if any that should be included on page one of the Moores' 1994 Form 1040.

The Moores received a $500 security deposit on their rental property in 1994. They are required to return the amount to the tenant.

Show Answer Hide Answer
Correct Answer: A

'A' is correct. $0. The security deposit is not taxable income because the Moores are required to return it when the tenant leaves. If the deposit is applied to damages in a later tax year, the portion the Moores retain would be income to them in the year they retain the deposit, and the money they spend to repair the damage would be a deduction to them.


Question No. 2

Doris and Lydia are equal partners in the capital and profits of Agee & Nolan, but are otherwise unrelated. The following information pertains to 300 shares of Mast Corp. stock sold by Lydia to Agee & Nolan:

The amount of long-term capital loss that Lydia realized in 1988 on the sale of this stock was:

Show Answer Hide Answer
Correct Answer: A

Choice 'a' is correct. $5,000 long term capital loss 'realized' in 1988 by Lydia. Be careful, and always check the question being asked. In this case, the question is how much of a capital loss Lydia realized in 1988.

Choice 'b' is incorrect. $3,000 represents the portion of the $5,000 realized loss that would currently be recognized unless there were additional capital transactions resulting in gains. Remember that the deduction for capital losses for an individual is limited to $3,000 each year.

Choice 'c' is incorrect. $2,500 represents the pre-1986 portion of the $5,000 realized loss that would have given rise to a recognized loss. Pre-1986 law required $2 of net long term loss to give the benefit of $1 of tax deduction. Current law gives a dollar-for-dollar deduction limited to $3,000 in any year.

Choice 'd' is incorrect. $0 would have been the amount of loss recognized if Lydia owned more than a 50% interest in the partnership. Losses realized on transactions between a partnership and a partner owning more than a 50% interest are not deductible as the parties would be considered related and any realized loss would be disallowed.


Question No. 3

Which one of the following statements is correct with regard to an individual taxpayer who has elected to amortize the premium on a bond that yields taxable interest?

Show Answer Hide Answer
Correct Answer: C

Choice 'c' is correct. The bond's basis is reduced by the amortization of the premium.

Choice 'a' is incorrect. For bonds acquired after 12/31/87, the amortization of the premium is an offset to interest income on the bond rather than a separate interest deduction.

Choice 'b' is incorrect. The amortization of the premium will reduce taxable income.

Choice 'd' is incorrect. The bond's basis will be decreased by the amortization.


Question No. 4

An individual had the following capital gains and losses for the year:

What will be the net gain (loss) reported by the individual and at what applicable tax rate(s)?

Show Answer Hide Answer
Correct Answer: A

Choice 'a' is correct. Specific netting procedures for capital gains and losses are outlined in the Internal Revenue Code for non-corporate taxpayers.

Gains and losses are netted within each tax rate group (e.g., the 15% rate group). The facts of this question have already performed this step for us.

Short-term Capital Gains and Losses

1. If there are any short-term capital losses (this includes any short-term capital loss carryovers), they are first offset against any short-term gains that would be taxable at the ordinary income rates.

2. Any remaining short-term capital loss is used to offset any long-term capital gains from the 28% grate group (e.g., collectibles).

3. Any remaining short-term capital loss is then used to offset any long-term gains from the 25% group (e.g., un-recaptured Section 1250 gains).

4. Any remaining short-term capital loss is used to offset any long-term capital gains applicable at the lower (e.g., 15%) tax rate.

Long-term Capital Gains and Losses

1. If there are any long-term capital losses (this includes any long-term capital loss carryovers) from the 28% rate group, they are first offset against any net gains from the 25% rate group and then against net gains from the 15% rate group.

2. If there are any long-term capital losses (this includes any long-term capital loss carryovers) from the 15% rate group, they are offset first against any net gains from the 28% rate group and then against net gains from the 25% rate group.

In this case, we are given net short-term capital losses of $70,000 to start with. Following the rules above, this first goes to offset any short-term gains at the ordinary income rates, but there are none in the facts. So, the next step is to offset the losses against any 28% rate gain long-term capital gains. The facts provide that there is $10,000 in gains from collectibles (taxable at the 28% rate). The remaining short-term loss ($60,000) is next used to offset the long-term capital gains at the 25% rate. The facts give us un-recaptured Section 1250 gains of $56,000 (taxed at the 25% tax rate). The remaining short-term capital loss is $4,000 ($70,000 - $10,000 - $56,000 = $4,000). The balance of the short-term capital losses is finally used to offset any capital gains taxed at the 15% tax rate, which the facts give us as $20,000. Therefore, after the $4,000 remaining short-term capital loss is applied to offset the $20,000 long-term capital gain taxed at the 15% tax rate, there is an amount of $16,000 remaining of long-term capital losses to be taxed at the 15% tax rate.

Choices 'b', 'c', and 'd' are incorrect, per the ordering rules discussed above.

Supplemental Questions


Question No. 5

Capital assets include:

Show Answer Hide Answer
Correct Answer: C

Choice 'c' is correct. Investment assets of a taxpayer that are not inventory are capital assets. The manufacturing company would have capital assets including an investment in U.S. Treasury bonds.

Choice 'a' is incorrect. Accounts receivable generated from the sale of inventory are excluded from the statutory definition of capital assets.

Choice 'b' is incorrect. Depreciable property used in a trade or business is excluded from the statutory definition of capital assets.

Choice 'd' is incorrect. Land is usually a capital asset, but when it is effectively inventory, as when it is used by a developer to be subdivided, it is excluded from the statutory definition of capital assets.


100%

Security & Privacy

10000+

Satisfied Customers

24/7

Committed Service

100%

Money Back Guranteed