- 163 Actual Exam Questions
- Compatible with all Devices
- Printable Format
- No Download Limits
- 90 Days Free Updates
Get All CPA Financial Accounting and Reporting Exam Questions with Validated Answers
| Vendor: | AICPA |
|---|---|
| Exam Code: | CPA-Financial |
| Exam Name: | CPA Financial Accounting and Reporting |
| Exam Questions: | 163 |
| Last Updated: | October 7, 2026 |
| Related Certifications: | Certified Public Accountant |
| Exam Tags: | AICPA Managment |
Looking for a hassle-free way to pass the AICPA CPA Financial Accounting and Reporting exam? DumpsProvider provides the most reliable Dumps Questions and Answers, designed by AICPA certified experts to help you succeed in record time. Available in both PDF and Online Practice Test formats, our study materials cover every major exam topic, making it possible for you to pass potentially within just one day!
DumpsProvider is a leading provider of high-quality exam dumps, trusted by professionals worldwide. Our AICPA CPA-Financial exam questions give you the knowledge and confidence needed to succeed on the first attempt.
Train with our AICPA CPA-Financial exam practice tests, which simulate the actual exam environment. This real-test experience helps you get familiar with the format and timing of the exam, ensuring you're 100% prepared for exam day.
Your success is our commitment! That's why DumpsProvider offers a 100% money-back guarantee. If you don’t pass the AICPA CPA-Financial exam, we’ll refund your payment within 24 hours no questions asked.
Don’t waste time with unreliable exam prep resources. Get started with DumpsProvider’s AICPA CPA-Financial exam dumps today and achieve your certification effortlessly!
On January 2, 1993, Quo, Inc. hired Reed to be its controller. During the year, Reed, working closely with Quo's president and outside accountants, made changes in accounting policies, corrected several errors dating from 1992 and before, and instituted new accounting policies.
Quo's 1993 financial statements will be presented in comparative form with its 1992 financial statements.
This question represents one of Quo's transactions. List B represents the general accounting treatment required for these transactions. These treatments are:
* Cumulative effect approach - Include the cumulative effect of the adjustment resulting from the accounting change or error correction in the 1993 financial statements, and do not restate the 1992 financial statements.
* Retroactive or retrospective restatement approach - Restate the 1992 financial statements and adjust 1992 beginning retained earnings if the error or change affects a period prior to 1992.
* Prospective approach - Report 1993 and future financial statements on the new basis but do not restate 1992 financial statements.
Item to Be Answered
Quo changed from LIFO to FIFO to account for its finished goods inventory.
List B (Select one)
Choice 'B' is correct. A change in accounting principle should be shown in the retained earnings statement of the earliest year presented as an adjustment of the beginning balance. All prior year financial statements are recast.
On January 1, 20X1, Pell Corp. purchased a machine having an estimated useful life of 10 years and no salvage. The machine was depreciated by the double declining balance method for both financial statement and income tax reporting. On January 1, 20X6, Pell changed to the straight-line method for financial statement reporting but not for income tax reporting. Accumulated depreciation at December 31, 20X5, was $560,000. If the straight-line method had been used, the accumulated depreciation at December 31, 20X5, would have been $420,000. Pell's enacted income tax rate for 20X6 and thereafter is 30%. The amount shown in the 20X6 income statement for the cumulative effect of changing to the straight-line method should be:
Choice 'd' is correct. A change in the method of depreciation is now considered to be both a change in method and a change in estimate. These changes should be accounted for as changes in estimate and handled prospectively. The new depreciation method should be used as of the beginning of the year of change and should start with the current book value of the underlying asset. No retroactive or retrospective calculations should be made, and no adjustment should be made to retained earnings.
And, certainly, the cumulative effect should not be reflected on the income statement any more.
Choices 'a', 'b', and 'c' are incorrect, per the above Explanation: .
The effect of a change in accounting principle that is inseparable from the effect of a change in accounting estimate should be reported:
Choice 'c' is correct. A change in accounting principle that is inseparable from a change in accounting estimate should now be reported as a change in estimate and thus as a component of income from continuing operations, in the period of change and future periods if the change affects both.
Distinguishing between a change in accounting principle and a change in accounting estimate is sometimes difficult. For example, a company may change from deferring and amortizing a cost to recording it as an expense when incurred because future benefits of the cost have become doubtful. The new accounting method is adopted, therefore, in partial or complete recognition of the change in estimated future benefits. The effect of the change in principle is inseparable from the effect of the change in estimate. Changes of this type are often related to the continuing process of obtaining additional information and revising estimates and are therefore considered as changes in estimates.
Choice 'a' is incorrect. Restating the financial statements of all prior periods would be done in the case of prior period adjustments (corrections of errors), changes in accounting principle (retrospective application), and changes in accounting entity (retrospective application).
Choice 'b' is incorrect. Correction of an error would be treated as a prior period adjustment.
Choice 'd' is incorrect. Separate disclosure after income from continuing operations would be done in the case of extraordinary items or discontinued operations. However, this disclosure would not be made 'in the period of change and future periods if the change affects both' but only in the period of the extraordinary item or discontinued operation.
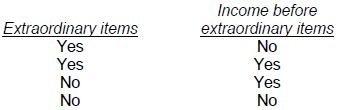
Earnings per share data should be reported on the income statement for:

Choice 'b' is correct. Yes - Yes.
Both the 'extraordinary items' and 'income before extraordinary items' should be shown with an earnings per share number on the income statement.
According to the FASB conceptual framework, which of the following statements conforms to the realization concept?
Choice 'b' is correct. Revenues and gains are realized when assets are exchanged for cash or claims to cash. SFAC 5 para. 83.
Choice 'a' is incorrect. Assigning depreciation in a production department is an example of allocating overhead. There is no realization associated with the assignment.
Choice 'c' is incorrect. The realization concept is integral to accounting for revenues and expenses and is not connected to collection of receivables.
Choice 'd' is incorrect. Assignment of overhead costs to products and thus to cost of goods sold is an example of matching. There is no realization associated with this assignment.
Security & Privacy
Satisfied Customers
Committed Service
Money Back Guranteed