- 1025 Actual Exam Questions
- Compatible with all Devices
- Printable Format
- No Download Limits
- 90 Days Free Updates
Get All CPA Auditing and Attestation Exam Questions with Validated Answers
| Vendor: | AICPA |
|---|---|
| Exam Code: | CPA-Auditing |
| Exam Name: | CPA Auditing and Attestation |
| Exam Questions: | 1025 |
| Last Updated: | October 4, 2026 |
| Related Certifications: | Uniform CPA Examination |
| Exam Tags: | AICPA Auditing management Financial Manager |
Looking for a hassle-free way to pass the AICPA CPA Auditing and Attestation exam? DumpsProvider provides the most reliable Dumps Questions and Answers, designed by AICPA certified experts to help you succeed in record time. Available in both PDF and Online Practice Test formats, our study materials cover every major exam topic, making it possible for you to pass potentially within just one day!
DumpsProvider is a leading provider of high-quality exam dumps, trusted by professionals worldwide. Our AICPA CPA-Auditing exam questions give you the knowledge and confidence needed to succeed on the first attempt.
Train with our AICPA CPA-Auditing exam practice tests, which simulate the actual exam environment. This real-test experience helps you get familiar with the format and timing of the exam, ensuring you're 100% prepared for exam day.
Your success is our commitment! That's why DumpsProvider offers a 100% money-back guarantee. If you don’t pass the AICPA CPA-Auditing exam, we’ll refund your payment within 24 hours no questions asked.
Don’t waste time with unreliable exam prep resources. Get started with DumpsProvider’s AICPA CPA-Auditing exam dumps today and achieve your certification effortlessly!
Which of the following is a management control method that most likely could improve management's ability to supervise company activities effectively?
This question presents independent factual situations an auditor might encounter in conducting an audit. List B represents the report modifications (if any) that would be necessary. Select as the best answer for each item, the action the auditor normally would take. The report modifications in List B may be selected once, more than once, or not at all.
Assume:
* The auditor is independent.
* The auditor previously expressed an unqualified opinion on the prior year's financial statements.
* Only single-year (not comparative) statements are presented for the current year.
* The conditions for an unqualified opinion exist unless contradicted in the factual situations.
* The conditions stated in the factual situations are material.
* No report modifications are to be made except in response to the factual situation.
Item to Be Answered
An entity changes its depreciation method for production equipment from the straight-line to a units-of production method based on hours of utilization. The auditor concurs with the change although it has a material effect on the comparability of the entity's financial statements.
List B
Report Modifications
Choice 'B' is the correct modification. Such changes should be described in an explanatory paragraph following the opinion paragraph without modifying the three standard paragraphs.
Which of the following internal control procedures most likely would deter lapping of collections from customers?
Choice 'c' is correct. Lapping is a defalcation in which a cash shortage is concealed by applying later customer remittances to a receivable account from which money was stolen. Lapping can be deterred by appropriate segregation of duties between receiving cash and posting to the accounts receivable ledger.
This makes it more difficult for the employee who is stealing the cash to cover it up through inappropriate remittance credits.
Choice 'a' is incorrect. Even with a lapping scheme, the dates of cash receipts journal entries and the dates of daily cash summaries would still agree, since the stolen funds would be excluded from both places and subsequent receipts would be included in both places.
Choice 'b' is incorrect. The authorization of write-offs of uncollectible accounts by a supervisor independent of credit approval would not deter lapping, since lapping schemes do not involve write-offs.
Choice 'd' is incorrect. Even with a lapping scheme, the daily cash summary would still agree with the sum of the cash receipts journal entries. Stolen funds would be excluded from both places and subsequent receipts would be included in both places.
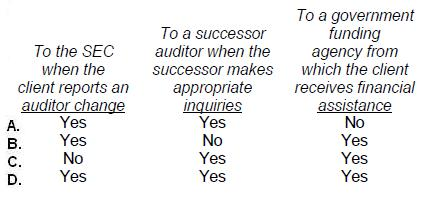
Disclosure of fraud to parties other than a client's senior management, those charged with governance, or its board of directors ordinarily is not part of an auditor's responsibility. However, to which of the following outside parties may a duty to disclose irregularities exist?

Which of the following questions would an auditor most likely include on an internal control questionnaire for notes payable?
Choice 'd' is correct. An internal control questionnaire for notes payable would likely ask if direct borrowings on notes payable are authorized by the board of directors.
Choice 'a' is incorrect. Whether collateralized assets are critically needed for the entity's continued existence is not a part of the control environment related to notes payable.
Choice 'b' is incorrect. The requirement for two authorized signatures is part of the disbursements internal control system, not the notes payable system.
Choice 'c' is incorrect. Whether the proceeds of notes payable are used for current or noncurrent assets is not a part of the notes payable internal control system.
Security & Privacy
Satisfied Customers
Committed Service
Money Back Guranteed